Coast FIRE vs. Barista FIRE: Key Differences Guide
When we dream of breaking away from the forty-year corporate grind, traditional early retirement often feels impossibly distant and unnecessarily restrictive. As exhausting workplace burnout pushes more of us away from extreme frugality, hybrid semi-retirement blueprints have rapidly surged in popularity. Yet, many aspiring early retirees find themselves confused between two distinct milestones: Coast FIRE and Barista FIRE. While both strategies reject the all-or-nothing corporate sprint, they rely on completely different financial mechanisms, risk tolerances, and weekly labor commitments. We will break down the essential mathematical distinctions, evaluate the critical longevity trade-offs, and help you select the ideal framework for your personal lifestyle.
affiliate link
Key Takeaways
Coast FIRE relies on leaving invested capital untouched to compound for decades, requiring active income solely to fund current living expenses.
Barista FIRE combines partial investment withdrawals with low-stress, part-time work to cover remaining living costs and access essential employee benefits.
Selecting between these pathways depends on current net worth, tolerance for sequence of returns risk, and willingness to maintain ongoing employment.
Mathematical Differences Between Coast FIRE and Barista FIRE Mechanics
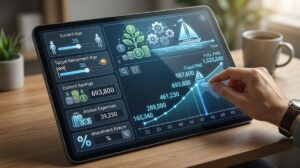
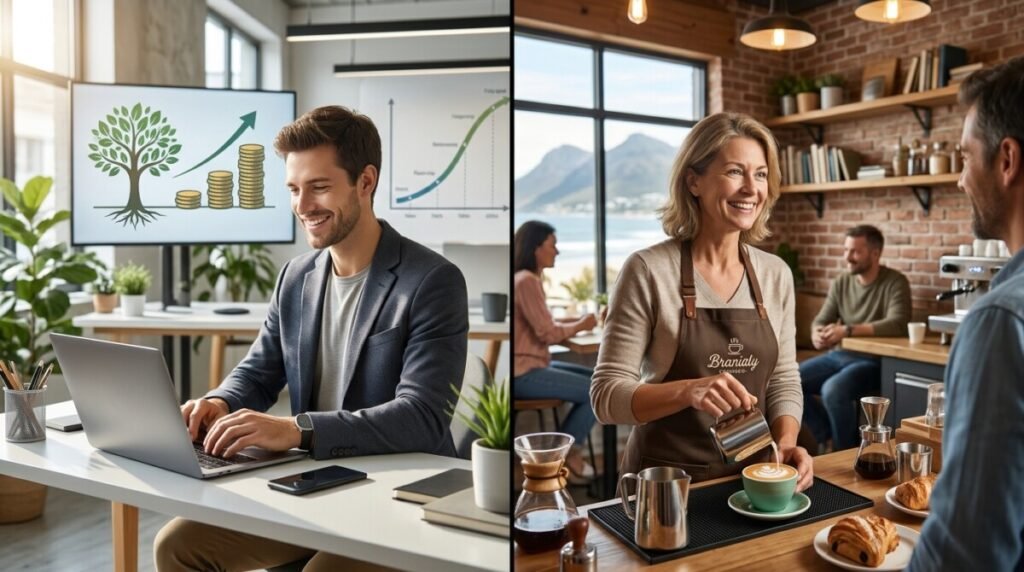
The fundamental divergence between these two financial frameworks lies in how an individual interacts with invested capital. In Coast FIRE, savers accumulate a designated milestone early and leave the principal untouched to compound until traditional retirement age. Barista FIRE, by contrast, pairs active part-time employment with immediate, partial portfolio withdrawals between two and three percent. Analysis from the Center for Retirement Research demonstrates that drawing early portfolio distributions permanently alters long-term wealth compounding curves. Therefore, Coast FIRE requires active earnings to cover all current living costs, while Barista FIRE uses investments to offset lower part-time wages.
Trade-Offs in Portfolio Longevity and Ongoing Labor Market Dependency
While both frameworks reduce corporate career strain, each model introduces distinct structural vulnerabilities that require careful risk evaluation. Barista FIRE exposes individuals to early sequence of returns risk, where withdrawing capital during market downturns can permanently deplete invested principal. Furthermore, relying on part-time service or retail roles for employer-subsidized health benefits leaves workers vulnerable to shifting corporate policies and scheduling cuts. Research from the Employee Benefit Research Institute indicates that individual health insurance premiums outside corporate group plans now average nearly six hundred dollars monthly. In contrast, Coast FIRE completely insulates existing investments from liquidation risk but demands sustained full-time or fractional earnings to pay current bills.
Choosing Your Semi-Retirement Strategy Based on Burnout and Savings
Choosing the optimal semi-retirement strategy requires matching personal net worth, vocational burnout levels, and desired weekly working hours. Exhausted professionals facing severe workplace fatigue frequently prefer Barista FIRE because downshifting to fifteen or twenty weekly hours provides immediate emotional relief. Conversely, professionals who enjoy their careers but reject aggressive savings rates thrive under Coast FIRE by eliminating future retirement contributions. A 2024 workplace report by Gallup revealed that sixty-seven percent of knowledge workers would accept reduced compensation for increased schedule autonomy. Financial advisors recommend conducting Monte Carlo portfolio simulations across both models before resigning to ensure personal cash reserves can withstand economic turbulence.
affiliate link
Conclusion
When we contrast Coast FIRE and Barista FIRE, we discover that financial independence does not require an all-or-nothing corporate sacrifice. Coast FIRE protects our compounding nest egg by keeping investments untouched, while Barista FIRE delivers immediate lifestyle liberation through part-time labor and partial distributions. Both pathways grant us the valuable autonomy to reclaim our physical health, escape toxic hustle culture, and spend meaningful time with our families. The ultimate decision rests on whether we prefer maintaining moderate active earnings today or tapping our portfolios early to work fewer weekly hours. We recommend calculating your Coast number tonight, evaluating your burnout levels, and selecting the semi-retirement path that best fits your goals.
https://focusofwellness.com/index.php/2026/01/20/firm-budget-tips-for-social-success/
https://fiscalfitnessflow.com/index.php/2026/10/29/micro-saving-strategies-build-an-emergency-fund/
Frequently Asked Questions
What is the main difference between Coast FIRE and Barista FIRE?
The main difference is portfolio interaction. Coast FIRE leaves your investment balance untouched to compound until traditional retirement age while active earnings cover daily living costs. Barista FIRE involves taking partial portfolio withdrawals right away, combining investment distributions with part-time work to pay for current living expenses.
Does Coast FIRE or Barista FIRE require a larger net worth?
Barista FIRE generally requires a larger upfront portfolio than Coast FIRE for the same age. Because Barista FIRE withdraws capital immediately, your investments have less opportunity to compound undisturbed. In contrast, Coast FIRE relies entirely on decades of future compound growth, requiring a substantially smaller starting balance.
Can you transition from Coast FIRE to Barista FIRE?
Yes, many professionals transition from Coast FIRE to Barista FIRE over time. After coasting for several years while investments expand, your portfolio may grow large enough to support partial withdrawals safely. This transition allows workers to gradually scale down working hours from full-time employment into low-stress, part-time arrangements.