Coast FIRE Calculator by Age: Exact Portfolio Targets

As we navigate demanding careers, many of us wonder how long we must keep pouring savings into retirement accounts. The constant pressure to maximize annual contributions often causes acute career burnout long before we reach traditional retirement age. A Coast FIRE calculator by age solves this challenge by pinpointing the precise investment balance where compound growth can take over. By establishing this financial tipping point early, we can comfortably redirect our active paychecks toward present living expenses or flexible work. Below, we unpack the mathematical benchmarks across life stages, examine key valuation risks, and show you how to apply the formula.
affiliate link
Key Takeaways
Coast FIRE calculates the exact balance needed today so that compound interest fully funds future retirement without further contributions. FinancialAha!
Time dramatically compounds capital, requiring roughly $142,000 at age twenty-five versus $377,000 at age forty-five for a forty-thousand-dollar annual retirement.
Modeling conservative real returns between five and six percent protects retirement projections against unexpected inflation and market downturns. NerdWallet
Benchmarking Your Coast FIRE Number by Age Across Real Return Models
The core formula discounts a target nest egg back to present value by dividing total retirement needs by one plus the real return raised to the remaining years. Assuming a standard four percent safe withdrawal rate, a sixty-thousand-dollar annual retirement requires a baseline portfolio of 1.5 million dollars at age sixty-five. At age twenty-five with a conservative five percent real return, an investor needs approximately 213,100 dollars, which drops to 145,800 dollars under a six percent growth model. By age thirty-five, those required balances rise to 347,100 dollars at five percent and 261,200 dollars at six percent as the compounding window contracts. At age forty-five, achieving the same objective demands 565,300 dollars at five percent or 467,700 dollars at six percent, demonstrating how waiting multiplies capital requirements.
Mathematical Limitations and Valuation Risks in Static Age Benchmarks
While static age benchmarks offer convenient reference targets, deterministic models dangerously assume that annual market returns arrive in perfectly uniform increments. In reality, sequence of returns risk can devastate a portfolio if severe market drawdowns occur shortly after an investor ceases retirement contributions. Historical market data demonstrates that starting a coasting phase during periods of elevated equity valuations frequently results in a lost decade of flat real returns. Furthermore, aggressive calculators that default to seven or eight percent real returns fail to account for investment expense ratios and unexpected inflationary spikes. Unforeseen lifestyle inflation and escalating middle-age healthcare premiums can also expand baseline spending, invalidating original portfolio projections before traditional retirement age.
affiliate link
Applying the Coast FIRE Formula to Design Flexible Career Transitions
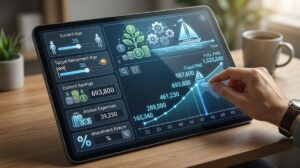
Savers can easily audit their personal milestone by entering the present-value formula into spreadsheet software using their current age and expected retirement timeline. Once accumulated assets reach the designated threshold, professionals can safely eliminate monthly retirement contributions and redirect their earned income toward flexible living expenses. Financial planners increasingly advise maintaining a small maintenance savings buffer of five percent to capture discounted equities during cyclical market downturns. Modern digital budgeting tools now automate dynamic real-return simulations, allowing workers to model spending scenarios between forty thousand and eighty thousand dollars annually. This quantitative clarity empowers mid-career employees to downshift into fractional roles, launch entrepreneurial ventures, or embrace rewarding sabbaticals with total financial peace.
Conclusion
When we examine our financial trajectory through a Coast FIRE calculator by age, retirement planning shifts from an exhausting marathon into an achievable near-term sprint. Discovering our personal tipping point proves that we do not need to hoard wealth endlessly when compound interest is already doing the heavy lifting for us. By adopting conservative five percent return assumptions and protecting our cash flow against inflation, we build genuine resilience into our long-term life plans. This mathematical milestone liberates us from corporate golden handcuffs, giving us permission to prioritize meaningful work and family presence today. We encourage you to calculate your personal age benchmark tonight, stress-test your spending targets, and reclaim ownership of your daily career choices.
https://fiscalfitnessflow.com/index.php/2026/02/26/protect-retirement-savings-beat-inflation/
https://focusofwellness.com/index.php/2025/11/13/digital-nomad-wealth-financial-planning-tips/
Frequently Asked Questions
What is the formula used in a Coast FIRE calculator by age?
The Coast FIRE formula divides your target retirement portfolio by one plus your expected real return, raised to the power of years until retirement. The target portfolio equals your annual retirement spending multiplied by twenty-five. In spreadsheets, enter =Target/(1+Return)^Years to calculate your milestone.
How much do you need to Coast FIRE at age 35?
To Coast FIRE at age thirty-five for sixty thousand dollars in annual retirement spending, you need approximately 347,100 dollars invested assuming a conservative five percent real return. Under a six percent return model, that required baseline drops to roughly 261,200 dollars for retirement at age sixty-five.
What real rate of return should you assume in a Coast FIRE calculator?
Financial experts recommend using an inflation-adjusted real return between five and six percent for stock index funds. While the S&P 500 historically averages around seven percent after inflation, choosing five percent provides a vital margin of safety against prolonged market stagnation and elevated living costs.